
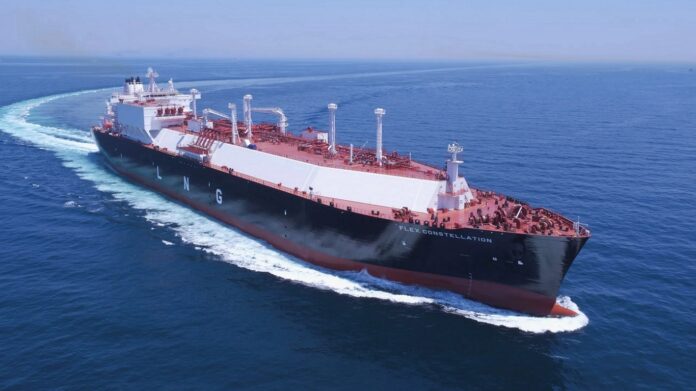
Qatar just signed a 28-year deal to buy American LNG from its own biggest rival, and Cheniere reports earnings in days. Whether that contract signals a permanent shift in global energy leverage or a one-time windfall depends on what management…
Cheniere Energy (NYSE:LNG | LNG Price Prediction) reports third-quarter results before the open on Oct. 29. Shares closed at $298.67 on Oct. 23, up 54.72% year to date. A new QatarEnergy deal and an ongoing global supply shock highlight the focus on this report.
Record Volumes, Twice-Raised Guidance and a Qatar Surprise
In the second quarter, revenue rose 24% year over year to $5.73B. Consolidated adjusted EBITDA climbed 27% to $1.80B. Cheniere shipped 184 cargoes, up from 154 a year earlier, as Stage 3 scaled up and the quarter ran without major maintenance. Management then raised 2026 EBITDA guidance to $7.90B to $8.40B. That was the second increase from the original $6.75B to $7.25B range.
The war in Iran has changed the market. At quarter-end, LNG tanker passages through the Strait of Hormuz were still under 10% of pre-conflict levels, and lower Qatar and UAE exports took out about 18 million tonnes of supply. Then, on Oct. 22, QatarEnergy agreed to buy 4 mtpa through 2054. Shares rose 9.16% over the past month.
Consensus Estimates
Metric Consensus Prior Year YoY Growth Q3 Normalized EPS $4.8263 $4.75 1.6% Q3 Revenue $5.36B $4.44B 20.7% FY2026 EPS $23.1645 $24.13 -4.0% FY2026 Revenue $22.64B $19.98B 13.3%
Train 7, Margins, and the Sabine Pass FID Clock
Analysts have moved estimates higher. The Q3 EPS consensus sat at $3.8134 90 days ago, and it picked up three upward revisions in the past 30 days.
First, I’ll be watching margins. Q2 got a lift from higher marketing margins and optimization around gas-price volatility. CFO Zach Davis called the long-term margin outlook “a fraction” of today’s levels, pointing to a $2.50 to $3 range. With less than 1 million tonnes of 2026 volume left unsold, guidance should narrow more than it moves.
Second, Train 7. At the last call, first LNG was imminent, with substantial completion expected ahead of its guaranteed date in 2027. Management also promised a 2027 production profile on this call and described the first full year with Stage 3 running as being in the mid-50s (million tonnes).
Third, Sabine Pass. Under the Qatar contracts, 1 mtpa depends on a Phase 1 FID, which management expects early next year once regulators sign off. Bechtel’s $4.7 billion contract is already under a limited notice to proceed. You should also look at how GAAP results read now that about 75% of IPM volumes are no longer marked to fair value.
Qatar Buying US LNG Rewrites the Long-Term Pitch
Qatar is Cheniere’s biggest long-term competitor, so its decision to sign on as a customer backs up the company’s premium contracting strategy. That matters because more than 100 million tonnes of new global capacity has reached FID since early 2025, and much of it has no buyer yet. If management links Train 7 progress with a firm FID timeline and a 2027 outlook that holds up as Hormuz flows recover, the market may start treating this year’s windfall as a lasting earnings base.
Contact [email protected] for any questions or corrections.
Source: 247wallst.com — article syndicated from the publisher’s feed; all rights remain with the original publisher.

