
Key Takeaways
- Bloom Energy fell 11% on Oct. 23 to close about 44% below its June 22 record, even after a third quarter that beat estimates.
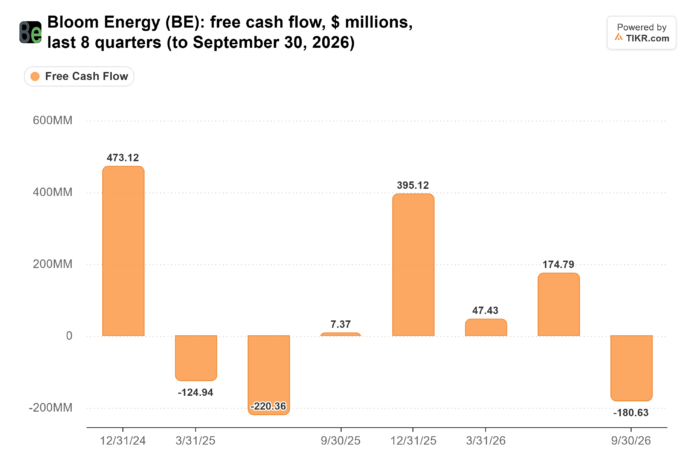
- Free cash flow turned negative at about $181 million, ending a run of four positive quarters.
- Gross margin reached 33.8%, and Bloom raised its 2026 revenue outlook to $4.4 billion to $4.6 billion, its third raise this year.
- At about 40.2x forward earnings, the stock still needs the fourth quarter’s record deliveries to turn into cash.
Bloom Energy (BE) has had a rough few weeks. Shares closed Oct. 23 at $193, about 44% below their record close of $346 on June 22.
The fuel cell maker fell 11% that day, right after a third quarter that beat estimates. Revenue more than doubled to $1.24 billion, and Bloom raised its full-year outlook for the third time this year.
So why the drop? Free cash flow turned negative, ending a run of four positive quarters. A broader slide in AI power stocks didn’t help either.
What did Thursday’s report deliver?
You can see the swings, and the turn, quarter by quarter…
Bloom Energy (BE): free cash flow, quarterly, Q4 2024 – Q3 2026 (TIKR)
Third quarter free cash flow came to negative $181 million as capex tripled to $153 million.
Customer deposits kept climbing, though. The drain came from contract assets, receivables and inventory, which all swelled as deliveries ramped.
CFO Simon Edwards said on the earnings call that the cash use is “not the beginning of a trend.” Year to date, free cash flow is still positive at about $42 million.
TIKR tracks 29 analysts on Bloom Energy. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Bloom Energy, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Bloom Energy’s Analyst Ratings
Margins are doing their part
Wider margins let more of each sale reach free cash flow. Bloom’s gross margin has widened every year since fiscal 2021, from 20.3% to 29.7% in fiscal 2025…
Bloom Energy (BE): gross margin (%), fiscal 2021–2025 (TIKR)
Third quarter gross margin hit 33.8%, its best of the year. The adjusted figure was 34.5%, just above management’s full-year goal of about 34%.
The outlook went up again
Bloom now expects $4.4 billion to $4.6 billion of revenue in 2026, up from $3.9 billion to $4.2 billion in July. Even the low end is more than double 2025’s $2.02 billion…
Bloom Energy (BE): revenue, actual and consensus estimates, $ billions, fiscal 2023–2028 (TIKR)
Bloom has booked $3.05 billion through September. So the new range implies fourth quarter revenue of about $1.35 billion to $1.55 billion.
Even 44% off its record, Bloom isn’t cheap at about 40.2x forward earnings. JPMorgan Chase cut its price target to $292 from $314 but kept its Overweight rating, saying Bloom’s execution “continues to impress.”
What comes next?
Big projects land unevenly, so one quarter’s cash flow can swing either way. If fourth quarter deliveries turn into cash, Friday’s drop will look like an overreaction. But if free cash flow stays negative, a bigger outlook won’t justify this multiple.
So what is Bloom Energy stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Bloom Energy could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!
Source: www.tikr.com — article syndicated from the publisher’s feed; all rights remain with the original publisher.

