
You’re likely aware that the ongoing proliferation of data centers means the already-strained utility industry won’t generate enough electricity for the planet’s near-future needs. And most investors may also know that the world is increasingly counting on a company called GE Vernova (GEV +7.54%) to supply the necessary power-generating equipment to shore up what Morgan Stanley says is a 38-gigawatt shortfall between now and 2028.
What you may not realize is that the matter isn’t solved by simply creating more electricity. Getting it from where it’s produced to where it’s needed is surprisingly complicated, and that challenge is made worse by the fact that the United States’ power grid — like most other nations’ grids — isn’t really ready to deliver. Deloitte says the nation’s power industry alone is poised to spend $1.4 trillion on infrastructure between last year and 2030, with comparable outlays expected through 2050.
Given this backdrop, GE Vernova’s recent decision to acquire Trench Group makes a lot of sense.
Details of the deal
It’s not a household name, although there’s a good chance your household regularly relies on one of its products without even realizing it.
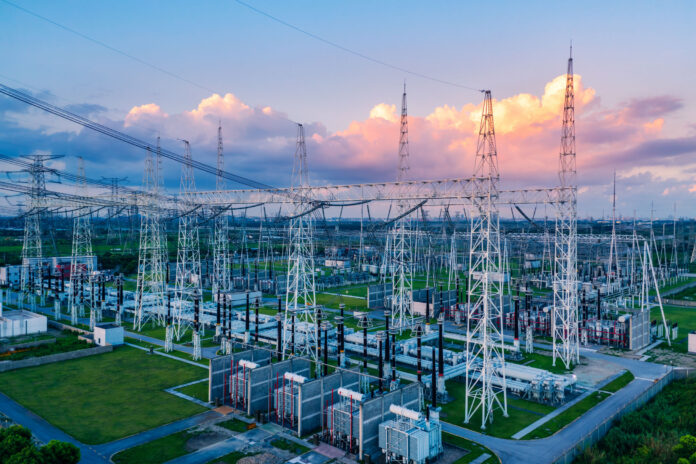
Trench Group makes high-voltage grid equipment… transformers, mostly — the kind you see on top of utility poles, or behind locked fences. Although GE Vernova is paying a hefty $9 billion for a company that only did $1 billion in business last year, Trench’s backlog also currently stands at around $5 billion, reflecting the same swell of demand that most companies in the power sector are experiencing at this time.
Image source: Getty Images.
It’s not just the future fiscal results of an industry-related enterprise that make this acquisition so savvy; GE Vernova already manufactures a range of utility transformers. This purchase adds production capacity, and in particular, foreign production capacity as well as existing relationships with overseas customers. Not only will the addition of Trench Group allow it to expand its portfolio, but it also enables vertical and horizontal integration that opens up new markets for GE Vernova’s already-robust soup-to-nuts offering.
Undoubtedly net-bullish
Creating synergies from a merger is easier said than done, particularly when the products in question are simple, and there’s already ample competition keeping pricing power in check. This dynamic certainly applies to this pairing.
GEV – GE Vernova
$927.29+$65.04 (+7.54%)
NYSE · As of 1:11 PM ET 11/03/26
Nevertheless, this deal has little to no downside, and plenty of potential upside. At the very least, the $9 billion investment — cash that GE Vernova more than has on hand — should pay for itself soon enough.
However, being the world’s biggest maker of natural gas turbines and one of the biggest names in power grid solutions, adding Trench only expands its marketing leverage within a power grid modernization market that industry research outfit Market.US expects to grow by more than 10% per year through 2035, only held back by slow funding and a lack of production capacity. To this end, GE Vernova’s third-quarter revenue jumped 27% year over year, while its backlog soared 96%.
Perhaps more important to interested investors, yes, this is another reason to be bullish on GE Vernova, even if not an overwhelming one that will produce an immediate measurable benefit.
Source: www.fool.com — article syndicated from the publisher’s feed; all rights remain with the original publisher.

