
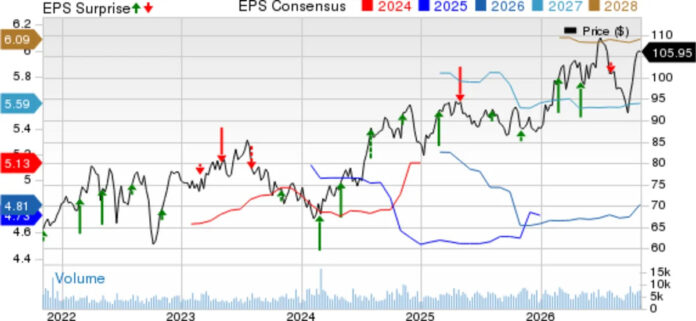
Pinnacle West Capital Corporation PNW reported third-quarter 2026 earnings of $3.49 per share, beating the Zacks Consensus Estimate of $3.40 by 2.65%. The bottom line increased 2.9% from $3.39 in the year-ago quarter, primarily driven by higher electricity sales, favorable weather and customer growth.
Total Revenues of PNW
Revenues totaled $1.97 billion, surpassing the Zacks Consensus Estimate of $1.94 billion by 1.65%. The top line increased 8.3% from $1.82 billion recorded in the year-ago quarter. Weather-normalized retail electricity sales grew 9.5%, reflecting robust demand across customer categories.
Pinnacle West Capital Corporation Price, Consensus and EPS Surprise
Pinnacle West Capital Corporation price-consensus-eps-surprise-chart | Pinnacle West Capital Corporation Quote
PNW’s Operating Income Grows Despite Higher Costs
Total operating expenses were $1.35 billion, up 9.1% from $1.24 billion in the prior-year quarter. Fuel and purchased power expenses increased 15.6% to $758.03 million, while depreciation and amortization expenses rose 8% to $242.50 million.
Operations and maintenance expenses declined 1.7% to $294.6 million from $299.6 million a year ago. Taxes other than income taxes decreased 3.6% to $56.31 million.
Operating income totaled $620.8 million, increasing 6.7% from $581.9 million in the year-ago period.
Total net interest expenses increased 12.2% to $124.8 million from $111.2 million, reflecting higher financing costs.
PNW’s Financial Position and Cash Flow
As of Sept. 30, 2026, cash and cash equivalents totaled $11.12 million compared with $6.60 million as of Dec. 31, 2025.
As of Sept. 30, 2026, long-term debt, less current maturities, increased to $10.16 billion from $9.21 billion as of Dec. 31, 2025.
Net cash provided by operating activities totaled $1.35 billion in the first nine months of 2026 compared with $1.33 billion in the corresponding period of 2025. Capital expenditures increased to $2.09 billion from $1.96 billion, reflecting ongoing infrastructure investments.
PNW’s 2026 Earnings Guidance and Growth Outlook
The company continues to expect its 2026 consolidated earnings in the range of $5.05-$5.25 per share. The Zacks Consensus Estimate for the same is pegged at $4.81.
Management now expects weather-normalized retail electricity sales growth of 8-10% in 2026, including a 5-7% contribution from large commercial and industrial customers.
The company projects adjusted gross margin of $3.45-$3.51 billion and adjusted operations and maintenance expenses of $1.09-$1.11 billion.
Arizona Public Service Company (APS) plans to invest $2.60 billion in 2026, followed by $2.65 billion in 2027 and $2.70 billion in 2028. The 2026 capital program includes $825 million for generation, $550 million for transmission, $765 million for distribution and $460 million for other projects.
APS has identified 5.8 gigawatts (GW) of committed additional electricity load, of which approximately 4.9 GW is not yet served. The company’s resource plan identifies approximately 15 GW of new generation and storage resources and 2.6 GW of transmission capacity requirements through 2041.
PNW’s Zacks Rank
Pinnacle West currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Upcoming Utility Releases
Duke Energy DUK is scheduled to report third-quarter 2026 results on Nov. 5, before the market opens. The Zacks Consensus Estimate for earnings is pegged at $1.87 per share, which implies year-over-year growth of 3.31%.
DUK’s long-term (three to five years) earnings growth rate is 6.38%. The Zacks Consensus Estimate for third-quarter 2026 sales is pinned at $8.90 billion, which implies a year-over-year improvement of 4.15%.
Evergy EVRG is set to report third-quarter 2026 results on Nov. 5, before the market opens. The Zacks Consensus Estimate for earnings is pegged at $2.30 per share, which implies year-over-year growth of 13.30%.
EVRG’s long-term earnings growth rate is 9.07%. The Zacks Consensus Estimate for third-quarter 2026 sales is pinned at $1.90 billion, which implies a year-over-year improvement of 4.71%.
PPL Corporation PPL is scheduled to report third-quarter 2026 results on Nov. 6, before the market opens. The Zacks Consensus Estimate for earnings is pegged at 53 cents per share, which implies year-over-year growth of 10.42%.
PPL’s long-term earnings growth rate is 5.26%. The Zacks Consensus Estimate for third-quarter 2026 sales is pinned at $2.44 billion, which implies a year-over-year improvement of 8.91%.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Pinnacle West Capital Corporation (PNW) : Free Stock Analysis Report
PPL Corporation (PPL) : Free Stock Analysis Report
Duke Energy Corporation (DUK) : Free Stock Analysis Report
Evergy Inc. (EVRG) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Source: finance.yahoo.com — article syndicated from the publisher’s feed; all rights remain with the original publisher.

