
Key Takeaways
- Munro Partners, a fund with $4.4 billion in US stocks, made Applied Materials (AMAT), Alphabet (GOOGL) and Quanta Services (PWR) its three biggest new or added positions in the quarter ended June 30.
- All three have fallen since, by 20% to 54%, but analysts’ average price targets sit 40% to 88% above the latest close.
- The main risk is the chip-equipment cycle: Applied Materials’ earnings have fallen from a previous peak, and its free cash flow hasn’t kept pace with its earnings this year.
- Applied Materials has the strongest case of the three: it trades below its five-year average multiple while analysts’ earnings estimates rise.
Applied Materials, Alphabet and Quanta Services were the three biggest new or added positions in Munro Partners’ latest 13F, for the quarter ended June 30 and filed Aug. 10.
All three have sold off hard since, and Wall Street still sees big upside in each of these tech stocks.
Munro, a fund manager based in Melbourne, held $4.40 billion of US stocks in 59 positions on June 30. A 13F leaves out stocks listed outside the US, so that’s only the US part of its portfolio.
Applied Materials got cheaper as estimates rose
Applied Materials was added to the fund by June 30. The fund bought 278,565 shares worth $201 million, making AMAT its fifth-largest position.
The stock is down 54% since then, most recently in a chip-stock rout that deepened after the midterms.
The 13F doesn’t show what Munro paid, or whether it still owns the shares.
Revenue rose 25% to $9.1 billion in the third quarter of fiscal 2026, which ended July 26, and management guided Q4 to $10.25 billion, up 51%.
Analysts raised their fiscal 2027 earnings estimate 13% from June 30 to Oct. 23, to $18.56 a share.
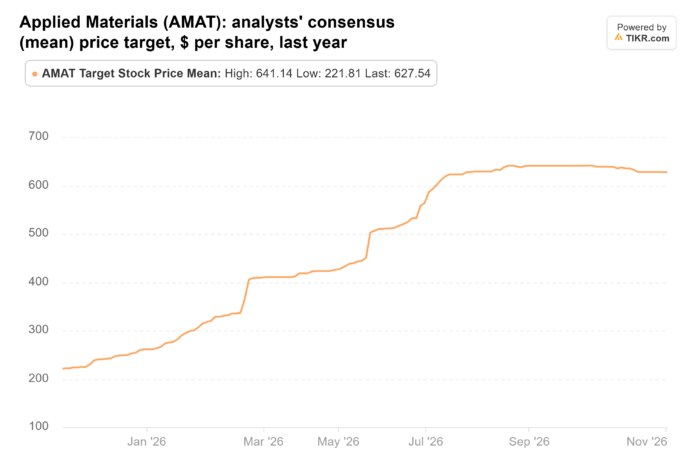
The Street’s average price target has barely come off its September peak:
Applied Materials (AMAT): analysts’ consensus (mean) price target, $ per share, last year (TIKR)
At $627, it’s 88% above Friday’s close of $333, and even the lowest target, $358, is above that close.
TIKR tracks 41 analysts on Applied Materials. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Applied Materials, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Applied Materials’ Analyst Ratings
Alphabet’s analysts haven’t flinched
Munro added 43% more Alphabet shares in the quarter, ending June 30 with 623,657 shares worth $223 million. At 5.1% of its US holdings, it was the fund’s third-largest position.
The stock is down 20% since then, and trades 44% below its 52-week high.
Alphabet has given investors more to like on AI. Its TPU chips now rank second only to Nvidia’s in computing power. Its Gemini model also just ranked No. 1, and a top venture capitalist says the best AI models take more than 80% of the spending.
The average target has held most of its climb from $315 a year ago:
Alphabet (GOOGL): analysts’ consensus (mean) price target, $ per share, last year (TIKR)
At $400, from 60 analysts, it’s 40% above Thursday’s close of $285, and the stock trades at about 20x forward earnings.
Munro more than tripled its Quanta stake
Quanta Services got the biggest increase. Munro added 207% more Quanta shares in the quarter, ending June 30 with 276,277 shares worth $199 million: 4.5% of its US stocks and its sixth-largest position.
The stock has fallen 25% since then, and is 46% below its 52-week high. Analysts spent the year raising their average target, from $435 a year ago to $766 now:
Quanta Services (PWR): analysts’ consensus (mean) price target, $ per share, last year (TIKR)
That’s 42% above Friday’s close of $541, from 31 analysts. But Quanta trades at about 26x forward earnings, the highest multiple of the three.
Applied Materials is the one I’d buy
All three trade well below the Street’s targets, but Applied Materials pairs the biggest upside with a multiple below its own average.
At about 19x forward earnings, it’s under its five-year average of 21x, and far below the 36x it reached in late July.
Chip-equipment earnings have peaked before: in fiscal 2019, Applied’s revenue fell 13%, its operating income fell 25%, and its forward P/E dropped to 8.2x at the October 2018 quarter-end.
Cash is lagging this year, too. Free cash flow was $3.6 billion in the first nine months of fiscal 2026, against $3.7 billion a year earlier, as receivables grew $2.5 billion.
If I could only buy one right now, it’d be Applied Materials. Its revenue growth is speeding up, and the stock is cheaper than usual.
Applied reports its fiscal Q4 on Nov. 12. If its outlook for Q1 of fiscal 2027 shows equipment sales flattening, I’d rethink it.
And Munro’s 13F for the quarter ended Sept. 30, due by Nov. 16, will show us whether the fund still held all three.
So what is Applied Materials stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Applied Materials could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Applied Materials for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!
Source: www.tikr.com — article syndicated from the publisher’s feed; all rights remain with the original publisher.

