
Key Takeaways
- ConocoPhillips raised its quarterly dividend 10.7% to $0.93 a share on Nov. 5, when it reported a third quarter in which its profit more than doubled.
- Free cash flow covers the higher dividend easily and still leaves room for large buybacks.
- The risk is the oil price: in fiscal 2020, free cash flow came to $90 million against $1.83 billion of dividends.
- The stock trades at 11x forward earnings, below its five-year average of 12x, so buyers aren’t paying extra for the raise.
ConocoPhillips (COP) raised its quarterly dividend 10.7% on Nov. 5, to $0.93 a share from $0.84. The new rate is payable Dec. 1 to shareholders of record on Nov. 16.
This is its second raise in about a year. The first was a 7.7% bump to $0.84 a share in late 2025. This one came with a third quarter in which profit more than doubled.
ConocoPhillips paid $3.36 a share over the last 12 months, which gives the stock a trailing yield of 2.5%. At the new $0.93 rate, StockAnalysis puts the forward yield at 2.77%. So for income investors, the question is whether free cash flow covers the bigger check and still leaves room for a bad year.
Profit more than doubled on higher prices
ConocoPhillips earned $4.0 billion in the third quarter, up from $1.7 billion a year earlier. The company said prices were the main reason: its average realized price rose 32% to $61.40 per barrel of oil equivalent, from $46.44. That more than made up for lower output, which fell by 97,000 barrels of oil equivalent a day from a year earlier, to 2.302 million.
Cash from operations came to $7.2 billion. After $3.1 billion of capital spending, free cash flow was $4.0 billion. Ordinary dividends took $1.0 billion of that, or a quarter, and buybacks took another $2.4 billion. Management says it’s on track to return 45% of its 2026 cash from operations to shareholders.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours for free as part of our new investment report, which you can access right here.
Plenty of room for $0.93
The raise adds roughly $400 million a year, which brings the dividend’s yearly cost to about $4.4 billion at the new rate.
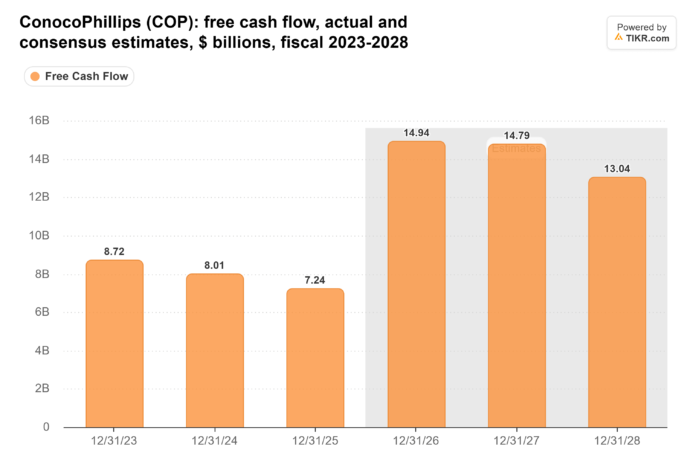
That’s well covered even by last year’s smaller cash flow. In fiscal 2025, ConocoPhillips paid $4.00 billion of common dividends out of $7.24 billion of free cash flow, which used up 55% of it. And analysts expect free cash flow over the next three years to be much higher than in any of the last three:
ConocoPhillips (COP): free cash flow, actual and consensus estimates, $ billions, fiscal 2023-2028 (TIKR)
Twelve analysts’ estimates put fiscal 2026 free cash flow at $14.9 billion, roughly double last year’s. I suspect most of that jump comes from the higher prices behind the third quarter. Either way, the raised dividend would take about 30% of that, and about a third of the $13.0 billion analysts expect for fiscal 2028. Management also reaffirmed its target of a $7 billion lift in free cash flow by 2029, with more growth after that.
The risk is the oil price
Over the last 10 years, free cash flow has covered the common dividend in most years, but it moves up and down with oil:
ConocoPhillips (COP): free cash flow vs. common dividends paid, $ billions, fiscal 2016-2025 (TIKR)
In fiscal 2016, free cash flow was negative $470 million against $1.25 billion of dividends. In fiscal 2020, it was $90 million against $1.83 billion. A crash like either one would leave the dividend uncovered for a while.
ConocoPhillips does have a cushion: $10.4 billion of cash and short-term investments at the end of the third quarter. Buybacks are also the bigger and more flexible part of what it returns, at $2.4 billion in the third quarter alone. If oil falls hard, I’d expect the buyback to shrink long before the dividend does.
Covered, and not expensive
Buyers aren’t paying up for the raise either. ConocoPhillips trades at 11x forward earnings, a bit below its five-year average of 12x:
ConocoPhillips (COP): forward (NTM) P/E, last 5 years (TIKR)
ConocoPhillips’ free cash flow covers the dividend easily, at the new rate and the old one. If free cash flow fell back to fiscal 2025’s $7.24 billion, the $4.4 billion dividend would use up about 60% of it. At analysts’ estimates for 2026 and 2027, it’s closer to 30%. I’d call this a safe and growing dividend, with a big buyback standing between it and a bad year for oil.
Of course, those estimates depend on oil prices holding up. ConocoPhillips’ fourth-quarter results, due early next year, will show us whether they did.
Forget ConocoPhillips: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And ConocoPhillips isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!
Source: www.tikr.com — article syndicated from the publisher’s feed; all rights remain with the original publisher.

