
Key Takeaways
- EOG Resources raised its quarterly dividend 7.8%, from $1.02 to $1.10 a share, first payable on Jan. 29, 2027.
- At the new rate of $4.40 a year, the dividend costs EOG about $2.3 billion a year. That’s roughly a quarter of the free cash flow analysts expect for 2026.
- In 2025, when oil was cheaper, dividends took 63% of EOG’s free cash flow, and free cash flow has covered the dividend in eight of the last ten years.
- The dividend looks safe and likely to keep growing, though a long slump in oil would slow the raises.
EOG Resources (EOG) just raised its regular quarterly dividend 7.8%, to $1.10 a share. The raise came with third-quarter results that showed record oil, NGL and natural gas volumes.
For an oil producer, the real question about any raise is whether the dividend makes it through the next drop in oil prices.
The details
The new dividend is payable on Jan. 29, 2027, to shareholders of record on Jan. 15. Over the last 12 months EOG paid $4.08 a share, which is a 2.8% trailing yield at Monday’s close of $147.83. The new rate of $4.40 a year lifts the forward yield to 3.0%.
EOG says it has paid a regular dividend for 28 straight years. That’s a record of paying, and StockAnalysis counts just 2 straight years of raises. So the cash behind the dividend tells you more than the streak does.
Chairman and CEO Ezra Yacob said the raise reflects “both the confidence in our business and our ability to support the higher dividend through commodity price cycles.” That second part is the claim worth testing.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours for free as part of our new investment report, which you can access right here.
Analysts see plenty of cash to cover it
EOG generated $2.2 billion of free cash flow in the third quarter, about 57% more than a year earlier, and paid out $544 million of it in regular dividends. Higher oil prices helped a lot. West Texas Intermediate crude averaged $85.68 a barrel in the quarter, up from $64.95 in the third quarter of 2025.
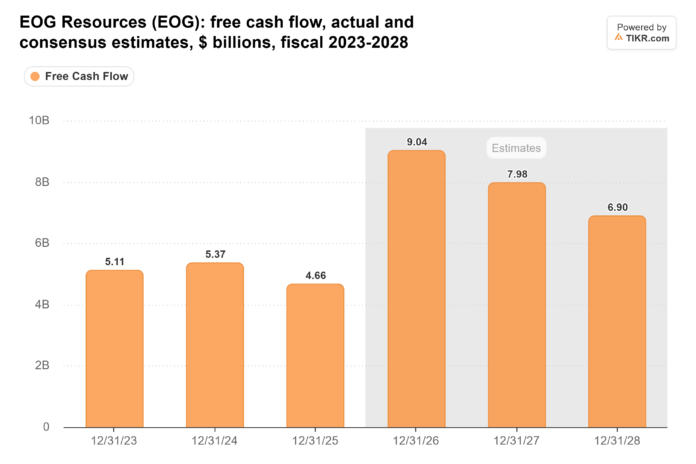
Analysts expect free cash flow to nearly double this year and to stay above 2025’s level through 2028:
EOG Resources (EOG): free cash flow, actual and consensus estimates, $ billions, fiscal 2023-2028 (TIKR)
At today’s share count, the $4.40 rate costs EOG about $2.3 billion a year. That’s about a quarter of the $9.04 billion analysts expect for 2026. It’s about a third of the $6.90 billion they expect for 2028, even with free cash flow falling back from this year’s high. And buybacks keep shrinking that bill: EOG bought back 7.0 million shares in the third quarter for $1.0 billion, at an average of $143 each.
A decade of coverage, with two misses
Those forecasts assume oil stays expensive, so it’s worth checking how EOG did when it wasn’t. Free cash flow covered EOG’s common dividends in eight of the last ten years:
EOG Resources (EOG): free cash flow vs. common dividends paid, $ billions, fiscal 2016-2025 (TIKR)
The two misses were 2016 and 2017, when free cash flow was negative or close to zero. The tall dividend bars in 2022 and 2023 are special dividends paid on top of the regular one in strong oil years. And in 2025, a year of cheaper oil, dividends took a comfortable 63% of free cash flow.
That’s the cushion Yacob is pointing to. In the third quarter, buybacks were nearly twice the size of the dividend. If oil drops, I’d expect EOG to cut buybacks long before it touches the regular dividend.
Safe, and still growing
The stock isn’t priced for a boom, either. EOG trades at 8.3x forward earnings, below its five-year average of 10x and well under the 15x it reached in February:
EOG Resources (EOG): forward (NTM) P/E, last 5 years (TIKR)
My read: investors expect oil prices, and EOG’s earnings, to come down from this year’s highs. That’s also the main risk to the dividend’s growth, since a long slump in oil would cut free cash flow and slow the raises.
Still, free cash flow covers the dividend with room to spare. Dividends took 63% of free cash flow in a weaker oil year, and on analysts’ estimates they’ll take about a third of it or less through 2028. The way I see it, this dividend is safe and still growing. Of course, a $4.40 dividend is easy to pay with oil at $85. EOG’s fourth-quarter report early next year will show how much room it leaves if prices slip.
Forget EOG Resources: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And EOG Resources isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!
Source: www.tikr.com — article syndicated from the publisher’s feed; all rights remain with the original publisher.

