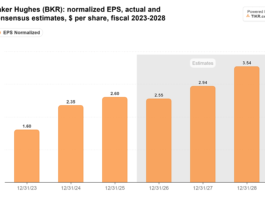
Baker Hughes (BKR) underperformed following its Q3 beat amid concerns about Industrial & Energy Technology order expectations, although management’s tendency to guide conservatively could leave room for material upside in the outlook, UBS Securities said in a note emailed Thursday.
The company’s updated Horizon 2 target of more than $50 billion in IET orders implies a slowdown from $22.5 billion in 2026 to a range of $14 billion to $15 billion for 2027 and 2028 each, according to the note.
Baker Hughes expects nearly $7 billion in Power Systems orders in 2026, implying orders of only $4 billion in 2027 and 2028 each. The brokerage believes this outlook is conservative given continued momentum in data center and power generation, as well as potential upside from NovaLT expansion, the note added.
UBS forecasts 2027 Oilfield Services & Equipment revenue to grow 4% to $14.56 billion, assuming a normalization in the Middle East. Adjusting for Waygate, it expects Industrial & Energy Technology revenue to grow 5% to $13.87 billion in 2027, and Chart Industries’ revenue to increase 4% to $4.1 billion, UBS said.
UBS kept a neutral rating on Baker Hughes with a $69 price target.
Source: finance.yahoo.com — article syndicated from the publisher’s feed; all rights remain with the original publisher.